


France’s debt woes threaten eurozone stability
French ten-year government bonds currently trade at around 150 basis points over Bunds, a spread that appears historically wide by domestic standards. For investors accustomed to viewing France as a core European sovereign, the dislocation offers an opportunity to buy low and wait for normality to return.
France’s Fiscal Challenges and Eurozone Cohesion
However, relying on past trends may be misleading, as current spreads might not adequately reflect future risks. A few years ago, concerns arose that France’s financial challenges and political divisions could undermine not only its own credit but also the stability of the eurozone. These issues remain relevant today, suggesting that historical data might not be a reliable indicator of future performance.
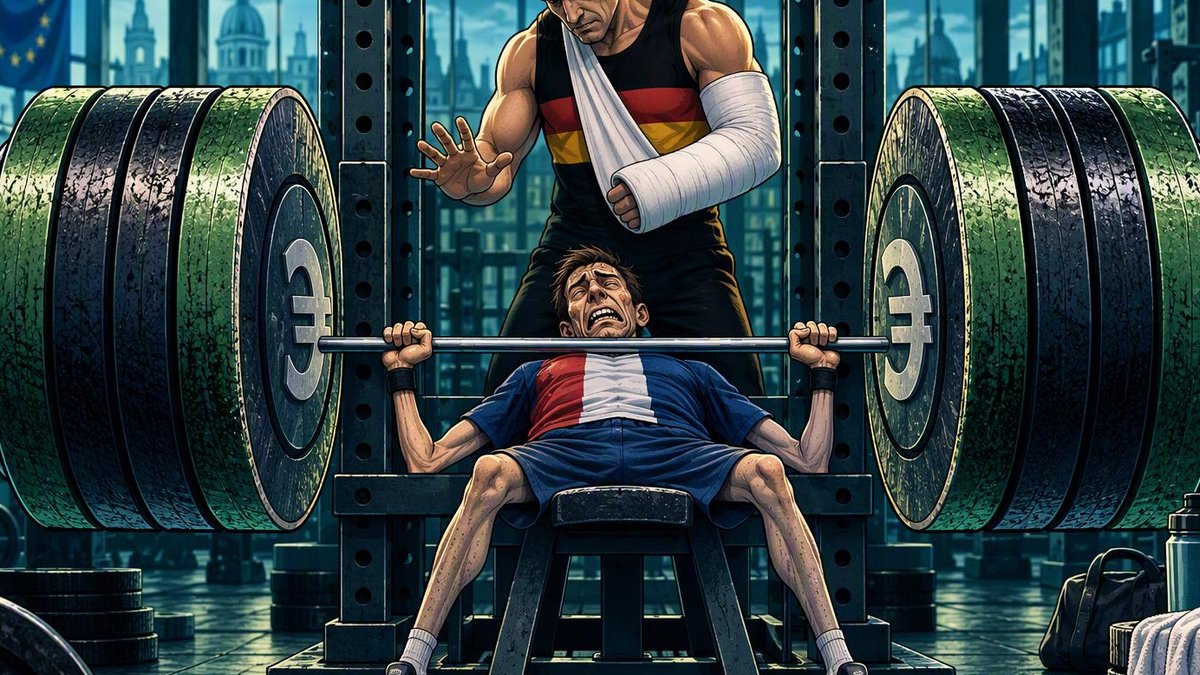
Recently, another key assumption about European sovereign debt has been challenged: the belief that Germany will always possess the economic and fiscal means to support other eurozone members. The combination of France’s earlier issues and this new uncertainty poses significant risks to the region’s financial stability.
Italy as a Reference Point
Investors might find it more useful to look at Italy’s historical spread over German bonds. During the sovereign debt crisis, Italian spreads surpassed 500 basis points. While this isn’t a prediction for France, it highlights how much spreads can widen when markets doubt fiscal sustainability and the reliability of European support mechanisms.
France’s past trading patterns may not accurately predict its future risks under different conditions. The main issue is moral hazard: providing unconditional support to France could reduce its incentive to improve public finances and might encourage other countries to seek similar treatment. On the other hand, withholding support could lead to higher borrowing costs, worsening France’s fiscal position and spreading stress throughout the monetary union.
ECB Tools and Political Realities
The European Central Bank’s tools, such as the Transmission Protection Instrument, do not fully resolve this dilemma. This instrument considers fiscal sustainability and compliance with European policies, aiming to address unwarranted market pressures. However, when repricing is driven by fundamental deterioration, intervention becomes more challenging. Sustained support would likely require France to make a concerted effort to restore its fiscal credibility.
The approaching presidential election complicates this dynamic. European institutions need confidence that the current government can deliver on commitments and that successors will honor them. While there’s no formal requirement for the ECB to wait, political clarity may be necessary before meaningful conditions can be sustained.
Shorting Spanish government bonds against duration-matched Bunds presents an interesting expression of this risk. Spain’s still relatively tight spread offers limited compensation for a broader fragmentation episode, and a narrower starting spread means less negative carry than shorting France. With a debt-to-GDP ratio of 100% and a minority government recently calling a snap election, Spain presents a potentially inexpensive way to position for investors questioning the eurozone’s collective insurance policy. However, it carries relatively limited downside compared to their current valuation.


